Aaron Kong
The land cost of S$1,178psf ppr for Thomson Reserve gives UOL, CapitaLand and SingLand immense pricing elasticity. With an estimated launch pricing of S$2,500–S$2,700psf, this District 20 mega-launch matches surrounding resale rates, giving investors rare value and an asymmetrical risk-reward play.

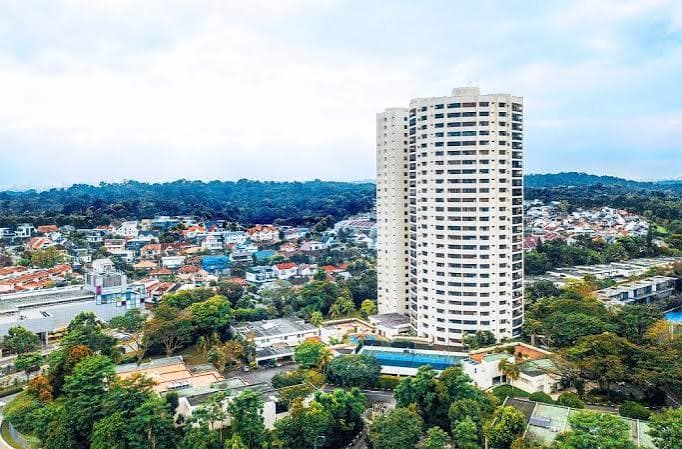
For real estate investors eyeing District 20, the upcoming launch of Thomson Reserve at Bright Hill Drive represents one of the most significant transactional entry points of the year. Developed by a powerhouse tier-1 consortium comprising UOL Group, CapitaLand Development, and Singapore Land Group, this massive 1,268-unit mega-development stands on the highly publicised former Thomson View en bloc site.
As the market prepares for the October 2026 VVIP preview, smart capital is moving past headline figures to dissect the underlying development economics. By analyzing the raw land cost, estimated breakeven margins and surrounding transaction data, we can evaluate whether Thomson Reserve presents a genuine value play or a fully priced premium asset.
The foundation of any real estate entry strategy begins at the land tender stage. The consortium secured the massive 540,000 sq ft plot for S$810 million. While a sub-billion dollar headline figure for five hectares of prime District 20 land raised eyebrows, the real indicator is the land rate.
After factoring in the necessary land betterment charges for intensification and the premium to top up the lease to a fresh 99 years, the final land cost sits at approximately S$1,178 per square foot per plot ratio (psf ppr).
To put this entry rate into perspective, a land cost of S$1,178 psf ppr for a Rest of Central Region (RCR) property is remarkably sharp. For context, several recent Outside Central Region (OCR) Government Land Sale (GLS) sites have breached the S$1,100 to S$1,300 psf ppr range despite being located further from primary city-fringe conduits. The consortium's ability to acquire this plot at a relative discount—12% below the owners' original S$918 million reserve price—gives the developers substantial pricing elasticity.
Early market consensus indicates that entry-level 2-bedroom configurations could start from approximately S$1.8 million, while standard 3-bedroom investor units are expected to launch from S$2.4 million. Premium multi-generational 4-bedroom and 5-bedroom suites featuring private lifts will scale upward from S$2,700 psf.
To determine if entering Thomson Reserve at S$2,500 to S$2,700 psf makes investment sense, we must look at local secondary market comparables.
The primary benchmark in the immediate vicinity is JadeScape, a similarly structured, large-scale District 20 leasehold mega-project. Resale units at JadeScape are currently trading at a robust S$2,525 to S$2,607 psf.
This creates a highly unusual market dislocation. Typically, a brand-new launch commands a 15% to 20% "new-to-resale" premium over surrounding sub-sale or recent resale developments. Because the Thomson Reserve land plot was acquired at S$1,178 psf ppr, the developer's estimated launch pricing matches—and in some configurations, slightly undercuts—the current active resale psf of its closest competitor. For an investor, entering a brand-new project at a price point on par with a 4-year-old resale development minimizes downside risk and creates a defensive buffer against market volatility.
A low entry price is meaningless without a viable capital appreciation exit strategy. Thomson Reserve’s long-term valuation is heavily insulated by impending infrastructural milestones that are not yet fully priced into District 20:
Immediate TEL Access: The site features direct, sheltered access to Upper Thomson MRT station (TEL), placing residents a seamless 14 minutes from Orchard Road and 22 minutes from the Central Business District. Walk-to-MRT specifications historically drive the highest gross rental yields, projected at 2.6% to 3.1% for 3-bedroom units upon TOP.
The 2030 Cross Island Line (CRL) Play: By 2030, the adjacent Bright Hill Station will morph into a major TEL x CRL interchange hub. Properties positioned next to dual-line interchanges historically experience a secondary wave of capital growth upon line completion, giving 2026 launch buyers a clear, predictable exit window.
With land costs structurally optimized at S$1,178 psf ppr, Thomson Reserve avoids the hyper-inflated launch premiums seen in other recent RCR developments. By aligning its launch pricing closely with the District 20 resale baseline, the project offers an asymmetrical risk-to-reward ratio. For transactional investors prioritizing entering at the bottom of a developer's margin wheel while securing top-tier structural connectivity, Thomson Reserve checks all defensive and growth-oriented boxes.
If you are looking at booking an appointment to view Thomson Reserve, contact me to book your VVIP slow to view the showflat now!
Contact: https://wa.me/6584881610
Aaron Kong is a highly dedicated real estate professional specializing in the buy, sell and renting of properties. Spanning both the residential and commercial sectors, Aaron serves a diverse clientel...